Italian Castles: a Buyer’s Guide to Typology, Survival, Reuse and Real Cost
Italian Castles: a Buyer’s Guide to Typology, Survival, Reuse and Real Cost
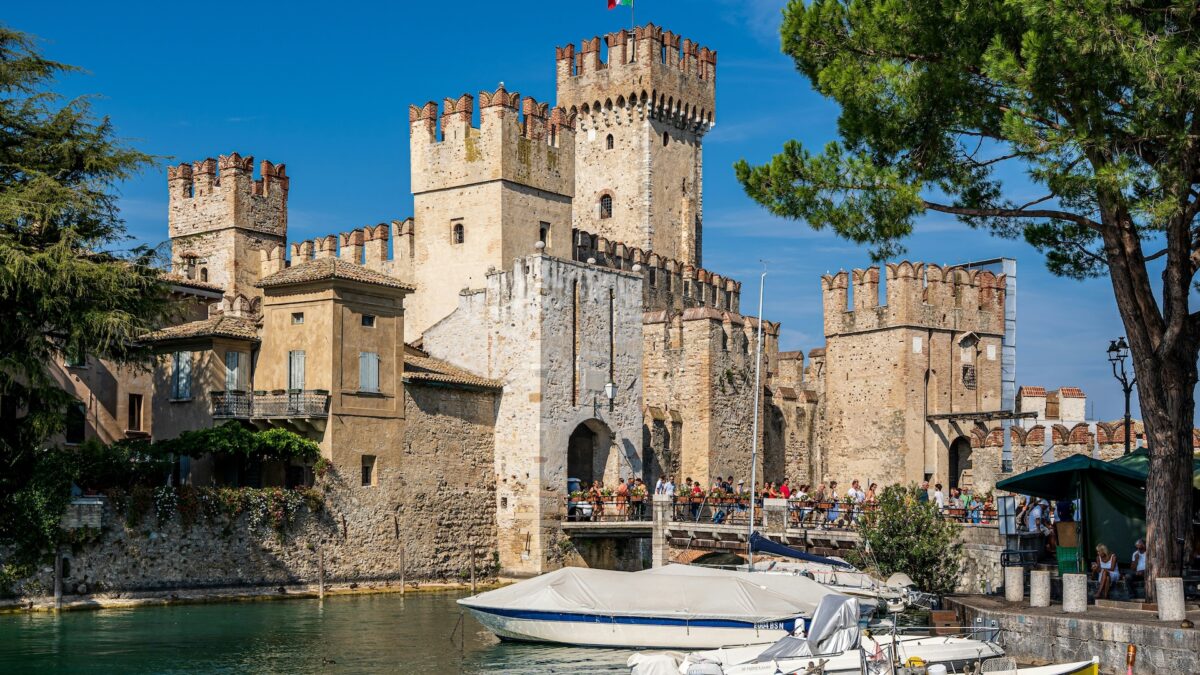
The fantasy is buying the castle.
The investment is buying its second life.
Italy has one of Europe’s deepest concentrations of fortified architecture, but there is no definitive national number for surviving castles. The Istituto Italiano dei Castelli is still building its national Atlante Castellano, a scientific census that deliberately includes intact fortifications, ruins and even sites known only through documentary evidence. The Institute itself warns that the data remain provisional and subject to field verification. In June 2024 the Atlas had already passed 10,350 structures, while current regional pages have continued to grow substantially. Piemonte alone now records 1,915 fortified sites, Emilia Romagna 1,741 and Lombardia 1,117.
That distinction matters for a buyer. A castle on a heritage map is not necessarily a habitable castle, and a castle on a property portal is not necessarily what an architectural historian would call a castle. The national Atlas encompasses castles, fortresses, towers, fortified houses, walled settlements and other defensive structures across an enormous chronological span. Current property portals use the term far more freely. JamesEdition, for example, currently groups more than 200 Italian properties under its castle category, while specialist broker Lionard currently shows roughly 60 publicly accessible castle listings plus additional confidential opportunities. The numbers cannot sensibly be treated as a national inventory because classifications, duplicates and listing turnover differ between platforms.
For an international buyer, the useful universe is therefore much smaller: castles that still possess meaningful architectural fabric, can legally be transferred, can support the desired use, and can be adapted without destroying the historic qualities that make them valuable in the first place. Italian heritage law can restrict alterations, require approval from the competent Soprintendenza and, in the case of protected cultural property, give the public authorities a right of preemption following a sale.
The central conclusion of this research is simple:
Do not buy the cheapest castle. Buy the castle whose architecture, condition, legal status and business model fit the same project.
That is precisely where an international buyer needs more than a real estate portal.
IRECOM can begin before the property search itself, by translating the buyer’s ambition into a search brief: private home, hospitality asset, wedding venue, wine estate, cultural destination or a hybrid of these.
What is actually still standing
Italian castles are not one category of building and they are certainly not one category of condition.
The national Atlante Castellano explicitly distinguishes structures that are localized and preserved, even where substantially altered, from sites surviving only through documentary evidence and sites that cannot be precisely located. Its research scope also deliberately includes ruins. This is one reason any claim that Italy contains a specific number of “castles” should be treated carefully.
Academic research makes the same point from another direction. University of Florence research on the Casentino landscape describes a medieval settlement system in which some castles still preserve a recognizable defensive form, while others survive only as fragments incorporated into later villages and buildings. Research from the University of Padua likewise treats castles through archaeology, written sources, building techniques, ruins and conservation rather than as a single homogeneous building type.
For a buyer, a simpler three category model is more useful.
| Buyer condition category | What it normally means | Likely opportunity | Main risk |
| Intact residence | Roofed and substantially enclosed, with the principal historic volumes intact. It may already be inhabited, used as hospitality or require modernization rather than reconstruction. | Private residence, boutique hotel, retreat, wedding venue, corporate hospitality | Hidden structural problems, obsolete systems, energy performance, access, fire safety, heritage restrictions |
| Partially ruined | Important portions survive but one or more wings, floors, roofs or towers may be damaged or missing. Some areas may be usable while others require structural intervention. | High potential adaptive reuse where surviving volumes already support a viable plan | The attractive acquisition price can conceal a much larger structural and permitting programme |
| Ruin | A masonry shell, archaeological structure or heavily collapsed complex with major loss of roofs, floors and serviceable interiors. | Cultural destination, landscape project, limited hospitality, event use, carefully designed contemporary insertion where permitted | Reconstruction may not be legally acceptable merely because historic walls once existed |
A ruin is therefore not simply an intact castle with more renovation work. It can be an entirely different planning proposition.
The restoration of the Castelli di Cannero on Lake Maggiore illustrates the principle. The project, reopened to the public in 2025 after more than a decade of work, deliberately preserved the character of the ruin rather than reconstructing an invented historical image. The reused fortress became an interactive cultural destination. That philosophy is extremely relevant to private buyers: sometimes the economically and architecturally intelligent reuse is to preserve a ruin as a ruin and put the revenue producing functions elsewhere in the estate.
The five castle families a buyer should recognise
The most important insight from the architectural sources is that castle typologies overlap. Many buildings began as military fortresses and were subsequently transformed into aristocratic residences. The Castello Svevo in Bari, for example, retains its medieval fortified core and towers but acquired Renaissance residential spaces and a bastioned exterior during later transformations. Cerro al Volturno likewise evolved from an early fortified position into a more comfortable noble residence with round artillery towers, halls and loggias.
| Type | What you are really buying | Typical architectural clues | Buyer perspective |
| Medieval fortress | A building conceived primarily around defence | Thick masonry, towers, keep, controlled entrances, defensive walls, elevated or strategic position | Spectacular identity, but often the hardest type to reconcile with modern circulation, bathrooms, lifts, large glazing and hotel servicing |
| Renaissance castello | A fortress transformed into, or conceived increasingly as, an elite residence | More regular rooms, ceremonial stairs, larger windows, decorated halls, courtyards, loggias and gardens | Often one of the strongest candidates for luxury residential or hospitality reuse |
| Fortified country estate | A defensive or seigneurial nucleus integrated with productive land | Castle or tower, farm buildings, cellars, courtyards, vineyards, olive groves, agricultural land | Potentially exceptional for a mixed hospitality, wine, olive oil and events strategy |
| Tower house | A compact vertical fortified residence | Tall narrow plan, heavy masonry, limited floor area, stacked rooms and constrained vertical circulation | Powerful as a private retreat, signature suite or small hospitality component, less suited to large operating programmes |
| Palazzo castle | A castle whose defensive identity has been overtaken by aristocratic residential architecture | Formal halls, suites, grand staircases, chapels, courtyards and decorative interiors, sometimes still wrapped by towers or walls | Usually the easiest castle family to position as high level hospitality, receptions, seminars or an important private residence |
Official catalog records show how tangible these distinctions are. A documented tower at Asciano in Tuscany uses load bearing brick construction over three levels. A twelfth century Pisa property is formally catalogued as a casa a torre. By contrast, Montalcino is recorded as a fourteenth century Gothic fortress, while the Aragonese castle at Castro in Puglia has a rectangular plan, four corner towers, a former moat and drawbridge and an internal courtyard.
That variation is not academic trivia.
It determines what you can do with the property.
Castle types and how to read them
A buyer walking through an Italian castle should resist the temptation to look first at frescoes, fireplaces and views.
Look up. Look down. Look at the walls.
Research at the University of Bologna on the castles of Romagna specifically studies construction materials, architectural elements and the evolution of fortified building techniques. Conservation teaching at the same university approaches historic buildings through foundations, masonry, vaults, floors, roofs, stairs, cracking, material deterioration, structural compatibility and building services. That is much closer to the checklist an acquisition team needs than a conventional luxury property inspection.
- Walls: Historic castle walls commonly use local stone, brick or combinations of the two, usually with lime based mortars. Material varies considerably by geography and construction phase. Brick has a major presence in the Po Valley and in parts of central Italy, while local stone dominates many hill, mountain and southern sites. Even within one building, later additions can introduce completely different masonry techniques. Academic research into fortified construction repeatedly uses those material differences to help establish chronology. The buyer needs to know whether masonry is merely visually weathered or structurally compromised. Moisture, failed joints, outward movement, poorly executed earlier repairs and incompatible cement based interventions can all turn an apparently solid wall into a significant conservation package. Conservation assessment should therefore precede design.
- Towers and keeps: The tower may be the most marketable photograph and the least efficient square metre. Keeps were defensive anchors. Their heavy masonry and limited openings can create extraordinary rooms but complicate escape routes, daylight, vertical circulation, plant distribution and accessibility. At Contignaco in Emilia Romagna, for example, the castle is organized around a square courtyard and includes a stone keep exceeding thirty metres in height. Today the same historic estate combines castle visits with its wine activity and tastings, showing how a tower can remain the identity marker while other portions of the estate carry the operating programme.
- Courtyards: Courtyards are among the most commercially useful elements in a castle. Historically they could serve defence, circulation, storage or productive purposes. The official catalog entry for Castro records an internal courtyard formerly used for agricultural storage. In a modern reuse, courtyards can become reception spaces, ceremony areas, dining spaces or the central orientation point of a hotel, provided capacity, weather, noise and emergency access are resolved.
- Chapels: A surviving chapel adds extraordinary narrative and experiential value, but it should never be treated as merely another reception room. Its protection, ownership, consecration status, decoration and permitted uses must be established individually. The restored Tuscan castle currently marketed near Arezzo at €6.75 million, for example, includes a chapel alongside hospitality related amenities and wine tasting spaces, demonstrating how such features can sit within a broader estate programme.
- Roofs: For the romantic buyer, roofs are almost invisible. For the project budget, they can be decisive. A functioning roof protects masonry, timber, frescoes, ceilings and floors simultaneously. Partial roof failure can trigger deterioration across multiple systems of the building. Historic roof structures may themselves possess heritage value, meaning replacement is not automatically the objective. The University of Bologna conservation framework explicitly places roofs among the structural and material systems requiring detailed assessment before intervention.
IRECOM takeaway: the correct first question during a castle viewing is not “How many bedrooms can this have?”
It is:
“Which historic elements are carrying the building, which are protected, and which parts can realistically accept a new function?”
Where the opportunity sits
No single map adequately captures Italian castles because different databases count different things.
The most ambitious current national effort is the Atlante Castellano of the Istituto Italiano dei Castelli. It aims ultimately to map fortifications from antiquity through the middle of the twentieth century and intentionally includes preserved sites, ruins and disappeared sites known through documentary sources. The Institute describes the project as continuously evolving and its current figures as provisional.
This produces some striking regional concentrations. Piemonte currently has 1,915 Atlas records, Emilia Romagna 1,741, Lombardia 1,117, Marche 543 and Tuscany 438. The Sicilian section reports 712 fortifications. Separately, the official cultural portal for Trentino describes roughly 300 castles in Trentino alone when disappeared, visible and visitable examples are combined.
Schematic infographic of regional distribution
The following is an order of magnitude map, not an official census of standing castles. Exact values shown without a range are live or explicitly published inventory figures found during this research. Rounded ranges marked with ≈ are editorial estimates produced by triangulating the national Atlas, regional heritage systems and published regional research. They should be used to understand relative density, not for statistical reporting. The national Atlas itself warns that its database is still being expanded and verified.
How many castles are there?
The geographic pattern also tells a buyer what kind of property to expect.
| Region | Documented inventory signal | Typical buyer relevant character |
| Valle d’Aosta | ≈ 100 to 200 | Alpine fortresses, towers and noble strongholds controlling valleys and routes |
| Piemonte | 1,915 Atlas records | Exceptional mix of castles, towers, fortified houses, ricetti and later noble residences, frequently tied to wine landscapes |
| Liguria | ≈ 300 to 500 | Compact hill and coastal fortifications, often dramatic but constrained by topography |
| Lombardia | 1,117 Atlas records | Feudal castles, Visconti and Sforza landscapes, fortified agricultural estates and major transformed residences |
| Trentino Alto Adige | ≈ 450 to 650, with roughly 300 reported in Trentino alone | Dense Alpine castle landscape, towers, medieval strongholds and Renaissance residential transformations |
| Veneto | ≈ 500 to 800 | Castles, towers and fortified settlements linked to plains, foothills and competing medieval territorial powers |
| Friuli Venezia Giulia | ≈ 400 to 600 | Border fortifications, hill castles, fortified estates and wine country residences |
| Emilia Romagna | 1,741 Atlas records | One of Italy’s richest castle belts, particularly strong for courtyard castles, rocche and estates capable of wine and hospitality integration |
| Toscana | 438 Atlas records | Fortresses, tower houses, castles and fortified estates embedded in globally recognised wine and rural landscapes |
| Umbria | ≈ 350 to 550 | Hilltop castles, fortified villages, rural estates and large stone complexes with strong retreat potential |
| Marche | 543 Atlas records | Rocche, hill fortifications and defensive settlements distributed between Apennines and Adriatic landscape |
| Lazio | ≈ 400 to 650 | Papal, baronial and medieval hill castles, often close enough to Rome to support events and destination hospitality |
| Abruzzo | ≈ 250 to 400 | Mountain castles and defensive settlements with strong landscape presence and generally lower international market visibility |
| Molise | ≈ 100 to 200 | Smaller castle network with prominent rocky strongholds and less saturated tourism positioning |
| Campania | ≈ 300 to 500 | Norman, Angevin and Aragonese layers, coastal and inland fortifications, sometimes monumental in scale |
| Puglia | ≈ 250 to 450 | Norman, Swabian and Aragonese fortifications, powerful geometric forms and numerous later palazzo transformations |
| Basilicata | ≈ 100 to 200 | Hill and ridge castles, frequently commanding extreme landscapes and secondary tourism territories |
| Calabria | ≈ 250 to 450 | Strategic hill and coastal fortifications reflecting successive Mediterranean powers |
| Sicilia | 712 published Atlas records | Exceptionally diverse Norman, Swabian, Angevin, Aragonese and baronial heritage across both cities and rural landscapes |
| Sardegna | ≈ 150 to 300 | Medieval strategic fortifications, towers and coastal defence systems with a distinct island context |
These numbers should not be compared with real estate listing counts. They describe a heritage universe. The market universe is a tiny moving subset.
The regional sources are revealing. Emilia Romagna’s official PatER heritage portal describes hundreds of castles and currently presents 130 visitable examples, emphasizing their role not only in landscape and history but also as present day tourism and cultural attractors. Lombardia maintains SIRBeC, its official cultural heritage information system. Friuli Venezia Giulia operates the ERPAC cultural catalog. Piemonte’s official tourism authority speaks of hundreds of castles and historic residences, with particularly strong concentrations through Langhe, Roero and Monferrato.
That produces a crucial buyer insight:
Tuscany is not the only castle market in Italy. It is the most internationally obvious one.
Piemonte, Lombardia, Emilia Romagna, Friuli Venezia Giulia, Umbria, Marche, Lazio and the South can all provide compelling alternatives, sometimes with a stronger relationship between acquisition cost, land, architectural importance and commercial potential. Current specialist listings already show castles in Tuscany, Emilia Romagna, Lazio, Lombardia, Friuli Venezia Giulia and Liguria, which reinforces the breadth of the active market.
What can a castle become
Adaptive reuse works when the new activity uses the castle’s strengths rather than fighting its geometry.
A fourteenth century keep does not need to become a conventional hotel corridor.
A courtyard does not need to become another bedroom wing.
A former agricultural complex should not automatically be stripped of the land that made it economically coherent for centuries.
Italy already provides working examples of castles used for museums, hospitality, wine production, tastings, concerts, weddings, exhibitions, cultural programming and private living. Trentino’s official cultural portal explicitly records castles used for theatre, concerts, exhibitions, historical performances, tastings and activities for families. Emilia Romagna records the wine related use of Contignaco. Lombardia highlights recovered castles supporting culture and events.
Reuse suitability matrix
| Castle type | Hospitality | Weddings and receptions | Events and seminars | Wine and olive oil | Agritourism | Private residence |
| Medieval fortress | Conditional | Strong where courtyards and access work | Strong | Weak unless attached to land | Conditional | Strong for the right buyer |
| Renaissance castello | Very strong | Very strong | Very strong | Strong where estate land survives | Strong | Very strong |
| Fortified country estate | Very strong | Very strong | Strong | Very strong | Very strong | Very strong |
| Tower house | Limited to small scale or signature accommodation | Weak | Conditional | Weak | Conditional if part of a larger farm | Strong |
| Palazzo castle | Very strong | Very strong | Very strong | Conditional | Conditional | Very strong |
| Major ruin | Conditional and potentially difficult | Strong as atmospheric external setting if safe and permitted | Strong for cultural programming | Strong only where productive land exists | Conditional | Low unless substantial lawful reconstruction is possible |
- Hospitality: The best hospitality castles have more than beautiful rooms. They need workable guest arrival, back of house circulation, kitchens, laundry, staff areas, fire safety, servicing, bathrooms, climate systems, acoustics, accessibility and an economically sensible ratio between usable guest space and total maintained area. The Italian hospitality cost evidence shows why historic structures matter. Horwath HTL analysed 50 cleaned Italian hotel projects representing more than €530 million of investment and over 5,570 rooms. Its dataset found average renovation expenditure of about €1,300 per square metre, but historic hotels averaged approximately €1,729 per square metre compared with about €887 for modern hotels. The report excludes land acquisition, VAT and administrative costs while including furniture, fixtures and equipment, so even those figures are not a complete castle project budget.
- Weddings and receptions: Castles naturally provide what event businesses spend heavily to manufacture: arrival drama, photographic identity, ceremony backdrops, courtyards, gardens and large historic rooms. But wedding feasibility is not a question of whether 150 people physically fit in the courtyard. It is a question of whether 150 guests can arrive, park or transfer, use sanitary facilities, dine, evacuate safely, hear amplified music without creating an unacceptable planning or neighbourhood conflict, and leave while the property continues to satisfy fire and public safety requirements. That distinction should be established before purchase.
- Events and seminars: Palazzo castles and Renaissance residences can be particularly strong because suites of reception rooms naturally support breakout spaces, presentations, dining and networking. Public adaptive reuse demonstrates the model. Padernello in Lombardia was recovered from abandonment and partial collapse and now supports theatre, exhibitions, concerts and cultural programmes, rather than being forced back into a purely residential function.
- Wine, olive oil and agritourism: This may be the most compelling model of all for the right rural estate because it reconnects the monument with the productive landscape that often sustained it historically. At Contignaco the castle and its wine estate support visits and tastings. Castello di Buttrio in Friuli Venezia Giulia combines a wine estate with hospitality, dining, tastings, corporate events and weddings. Castello di Vicarello in Tuscany integrates hospitality with organic vineyards and centuries old olive groves. Italy’s national agritourism legislation explicitly links agritourism with agricultural activity and allows connected hospitality, food, product tastings and recreational, cultural and educational activities, while regional rules determine detailed requirements. This makes the model powerful, but it also means that simply owning rural land beside a castle does not automatically make the property an agriturismo. The agricultural business structure and the applicable regional framework matter.
The smartest castle business may therefore contain several revenue layers rather than one: rooms, events, food, wine, experiences and agriculture.
And the smartest acquisition process starts by testing those layers before the offer is unconditional.
Heritage constraints and total project economics
This is where romance has to stop and underwriting has to begin.
Italian cultural heritage protection is governed principally by Legislative Decree 42 of 2004, the Codice dei beni culturali e del paesaggio, which remains the central statutory framework and was updated through 2026.
For a formally protected property, the Soprintendenza explains that Article 20 prohibits destruction, damage and uses incompatible with the cultural character or conservation of the property. Article 21 requires prior authorization for works on protected cultural property. The Monza Brianza and Pavia Soprintendenza states that applications for building conservation projects require substantial documentation, potentially including surveys, assessment of materials and deterioration, structural distress, consolidation proposals, reuse plans, comparative drawings and building services. It also indicates that architectural conservation projects must be signed by a qualified architect.
Protection can extend beyond the walls. The Parma and Piacenza Soprintendenza explains that indirect protection measures can regulate distance, perspective, light and the environmental setting around cultural property. Separate landscape protection may also apply. Article 146 of the Heritage Code requires authorization before works that affect protected landscape values may begin.
And there is one transaction issue international buyers frequently underestimate: preemption.
When ownership or possession of protected cultural property is transferred, the transfer must be reported to the Ministry under Article 59. The Ministry may purchase an asset sold for consideration at the price established in the transaction. The Milan Soprintendenza states that the right normally must be exercised within 60 days after receipt of the transfer declaration, or within 180 days when a declaration is late or incomplete. While that period is running, the sale is subject to the possible exercise of the public right.
That is not a reason to avoid protected castles.
It is a reason to structure the acquisition correctly.
From search to hospitality opening
- Define the use and total capital budget
- IRECOM targeted property search
- Historic and cadastral screening
- Check cultural and landscape protection
- Architectural and structural survey
- Test hotel, events or agricultural feasibility
- Preliminary concept and cost plan
- Offer with appropriate due diligence
- Notarial purchase and heritage transfer procedure
- Soprintendenza and municipal approvals
- Detailed design and contractor procurement
- Conservation and building works
- Fire, health, safety and operating compliance
- Hospitality SCIA and required registrations
- National CIN registration where applicable
- Opening
The operating layer is separate from the conservation layer. Current national standardized administrative modules include SCIA procedures for hotel and nonhotel accommodation. The Ministry of Tourism now operates the national accommodation database through which hospitality properties receive the CIN identification code.
Fire safety becomes particularly important at castle scale. The National Fire Brigade identifies accommodation establishments with more than 25 beds within activity 66 of the national fire prevention regime. Even smaller accommodation structures remain subject to applicable safety measures.
The total project cost is the number that matters
The asking price is simply the entry ticket.
For a castle, total project cost can include acquisition, taxes, notarial and advisory costs, surveys, design, permissions, structural consolidation, roofs, masonry conservation, new services, fire strategy, lifts or accessibility interventions where feasible, landscaping, kitchens, furniture, operating equipment, professional fees, financing and contingency.
| Cost layer | Practical screening allowance | What can move the number |
| Purchase | Current specialist marketed examples run from lower seven figure projects into many millions, with prime restored castles reaching roughly €10 million and beyond | Region, condition, land, wine production, hospitality licence, size, restoration quality, views, privacy and brand position |
| Purchase taxes | Transaction specific. A common nonconcessionary residential purchase from a private seller uses 9 percent registration tax on the applicable tax base plus fixed mortgage and cadastral taxes. VAT treatment differs when the seller is a business and can be materially different for A1, A8 and A9 luxury classifications | Seller status, cadastral category, applicable tax base, land, commercial components, agricultural components and ownership structure |
| Surveys and professional team | Budget separately before acquisition and through design | Measured survey, structural engineering, heritage specialist work, geology, archaeology, landscape design, fire engineering, services engineering and project management |
| Intact building modernization | Rough screening level around €800 to €1,500 per square metre before unusually complex conservation | Systems, bathrooms, heating and cooling, roof, finishes, accessibility and structural findings |
| Deep historic conversion | Rough screening level around €1,700 to €3,500 per square metre | Conservation intensity, structural consolidation, services routing, decorative surfaces, fire compliance and bespoke workmanship |
| Complex ruin or exceptional luxury conversion | For early feasibility, stress test at roughly €3,500 to €6,000 per square metre or more where extensive reconstruction and specialist conservation are involved | Missing floors and roofs, unstable masonry, archaeological requirements, access, remote logistics and luxury fit out |
| Furniture and operating equipment | Separate allowance required even when construction benchmarking includes some furniture | Hotel positioning, kitchens, lighting, bespoke joinery, antiques, guest rooms, event equipment and external furniture |
| Contingency | A meaningful reserve is essential. For early acquisition modelling, 15 to 25 percent of works is a reasonable stress test for a protected building, with a higher reserve for ruins | Hidden voids, archaeology, moisture, concealed timber decay, structural discoveries and approval conditions |
The construction bands above are feasibility screening ranges, not contractor quotations. The lower end is informed by current Italian residential renovation benchmarks, while historic hospitality evidence provides a more relevant centre of gravity. Horwath HTL found historic hotel renovation averaging about €1,729 per square metre. A recent Venetian palazzo restoration reported structural works alone at approximately €3,500 per square metre, demonstrating how easily highly constrained historic buildings can move beyond conventional renovation benchmarks.
Official regional price lists provide the more rigorous basis when a real project reaches cost planning. Tuscany’s 2026 public works price list is currently valid and contains construction and specialist work items. Emilia Romagna’s corresponding 2026 schedule includes specialist labour for historic architectural assets, stone conservation, consolidation, cleaning, masonry, vaults, roofs and structural works.
On the acquisition side, current specialist marketing demonstrates how wide the price envelope can become. Lionard presently advertises examples including a Ligurian fortress at approximately €1.98 million, an Arezzo castle around €4.8 million, another restored Tuscan castle around €6.75 million and a Chianti medieval castle around €9.8 million, alongside many assets marketed without a public price. Idealista currently shows, among other examples, an Umbrian castle requiring renovation around €2.5 million. These are asking prices, not evidence of completed transactions.
Tax also needs to be modelled property by property. The Agenzia delle Entrate states that a standard residential purchase from a private seller normally attracts registration tax at 9 percent plus fixed mortgage and cadastral taxes, while VAT and fixed tax rules differ in taxable business sales, including specific treatment for A1, A8 and A9 properties. Castle transactions can include agricultural land, commercial accommodation and multiple cadastral units, so a generic residential calculation should never be treated as the final tax model.
This is the IRECOM proposition in one sentence:
Do not ask whether you can afford the purchase price. Ask IRECOM to help establish whether you can afford the completed project you actually want.
Six real reuse stories and source base
The strongest argument for buying a castle is not that these buildings have survived.
It is that some of them have learned to produce value again.
- Reschio, Umbria: from historic stronghold to destination resort
Castello di Reschio demonstrates the full luxury hospitality model. The documented construction programme ran from 2015 to 2020 and involved approximately 10,500 square metres. Contractor GARC describes structural consolidation and conservation of masonry, stonework, plaster, floors, windows and archaeological remains together with new electrical, mechanical and water systems. The result is a luxury resort integrated into a much larger historic estate.- Before: historic castle requiring major conservation and functional transformation.
- After: destination luxury hospitality with the monument operating as the emotional centre of a broader estate.
- Published budget: not disclosed in the sources reviewed.
- Buyer lesson: at this level the building, landscape, interiors, craftsmanship, servicing and brand concept become one project. The castle cannot be costed as an isolated shell.
- Padernello, Lombardia: from collapse to cultural engine
Padernello offers a different and perhaps more instructive model. The castle had been abandoned in 1965 and suffered serious collapses in 2002, affecting major spaces including halls, kitchens, library and chapel. In 2005 it was acquired for approximately €1.43 million through a public and private ownership structure. By 2018 approximately 70 percent of the complex had reportedly been restored, with restoration expenditure of about €3.5 million. The castle subsequently supported theatre, exhibitions, concerts and other cultural programmes and recorded about 40,000 visitors in 2017. A further €200,000 project reported in 2025 targeted the historic stables for tourism and visitor functions, illustrating an important reality of castle reuse: investment continues after reopening.- Before: abandonment, deterioration and major collapse.
- After: public cultural destination and event venue.
- Published capital: approximately €1.43 million acquisition plus about €3.5 million restoration by 2018, with later investment continuing.
- Buyer lesson: a castle does not need bedrooms to create economic and territorial value. Cultural programming can itself become the reuse model.
- Castello di Ugento, Puglia: from dormant palazzo castle to hotel, food and culture
Ugento is a compelling example of the palazzo castle model. The property is a seventeenth century aristocratic palazzo built over earlier Norman fortress foundations. After a long period of dormancy, it underwent an extensively reported restoration costing approximately US$12 million and was repositioned as a boutique hotel with a cooking school and art programme, with weddings forming part of the commercial proposition.- Before: historic aristocratic complex with earlier fortified fabric, no longer functioning at its potential.
- After: hospitality, culinary education, culture and private events under one destination identity.
- Published capital: approximately US$12 million.
- Buyer lesson: the strongest business plan often monetizes several attributes of the castle instead of relying exclusively on room revenue.
- Tabiano, Emilia Romagna: fortress, borgo, spa and hospitality
Tabiano shows how a medieval defensive complex can accommodate contemporary hospitality without pretending that the new interventions are medieval. The architectural project describes an eleventh century castle and its borgo evolving from a military fortress into a Relais de Charme. The programme includes approximately 15 hotel rooms and a spa inserted into the historic setting, with contemporary work designed to remain recognisable while using compatible materials including local brick, stone and iron. A separate current programme for restoration of the castle park and gardens carries a reported value of approximately €1.60 million through the PNRR framework. That figure relates to the landscape component, not the total historic hotel conversion.- Before: medieval fortress and associated historic settlement.
- After: hospitality, wellness and destination reuse.
- Published capital: total hotel conversion budget not found; related park and garden restoration approximately €1.60 million.
- Buyer lesson: adaptive reuse is not necessarily about disguising the twenty first century. It is about inserting contemporary functionality without erasing historic legibility.
- Castello di Buttrio, Friuli Venezia Giulia: wine estate plus rooms plus events
Buttrio demonstrates why the fortified country estate can be commercially stronger than a stand alone castle. Published hospitality information describes an estate of approximately 38 hectares integrating wine production with a boutique hotel, agritourism accommodation, dining, tastings, vineyard experiences, corporate meetings, conferences, team activities, weddings and gala dinners.- Before: historic castle and productive agricultural estate.
- After: integrated wine tourism, hospitality, food and events destination.
- Published capital: not disclosed in the reviewed sources.
- Buyer lesson: the land may be as important as the castle. Wine, food and agriculture create reasons to visit repeatedly, while the castle supplies identity and pricing power.
- Castello di Casole, Tuscany: estate scale hospitality
Castello di Casole illustrates the institutional luxury end of the market. Following acquisition by Belmond, the estate was reported as a 39 room hospitality property within roughly 1,500 acres containing vineyards and olive groves. A four year refurbishment programme of approximately €7.3 million was announced, including work extending beyond the principal hotel into estate accommodation.- Before: established historic estate and hospitality asset requiring repositioning and renewed capital.
- After: internationally positioned luxury resort integrated with the Tuscan landscape and agricultural identity.
- Published refurbishment programme: approximately €7.3 million.
- Buyer lesson: even an already operating castle is not necessarily a finished investment. Repositioning, interiors, guest expectations and landscape can demand substantial new capital after acquisition.
What these six projects really prove
They do not prove that every castle should become a hotel.
They prove almost the opposite.
Reschio uses hospitality. Padernello uses culture. Ugento combines hospitality with food and art. Tabiano adds wellness. Buttrio connects wine, rooms and events. Casole operates at estate scale.
The common denominator is not the business model.
It is the fit between building, landscape, permitted use, capital and concept.
That is why a castle search should not begin with:
“Show me castles for sale in Italy.”
It should begin with:
“This is what I want the property to become. Which Italian castles can actually become it?”
That is a fundamentally different search.
And it is the search IRECOM should run for the buyer.
Research source table
| Source | Type | Research value |
| Istituto Italiano dei Castelli, Atlante Castellano d’Italia | National specialist heritage institution | National methodology, regional distribution, distinction between preserved sites, ruins and documentary sites |
| Ministero della Cultura, Catalogo Generale dei Beni Culturali | Primary national heritage catalog | Individual castle architecture, chronology, materials, ownership and protection status |
| Soprintendenze Archeologia Belle Arti e Paesaggio | Primary regulatory authority | Authorization procedures, conservation documentation, indirect protection and transfer preemption |
| Normattiva, Legislative Decree 42 of 2004 | Official legislation | Current legal framework governing cultural and landscape heritage |
| University of Padua | Academic research | Castle archaeology, documentary evidence, construction techniques, ruins and conservation |
| University of Florence | Academic research | Medieval castle diffusion and landscape formation in Casentino |
| University of Bologna | Academic research and conservation teaching | Construction materials, architectural elements, structural assessment and conservation methodology |
| Politecnico di Torino | Academic architectural research | Distinction among towers, castles and fortified houses in Piemonte and Valle d’Aosta |
| PatER, Regione Emilia Romagna | Official regional inventory | Regional castle network, conservation interventions and visitor reuse |
| SIRBeC, Regione Lombardia | Official regional inventory | Architectural heritage records and regional cultural asset mapping |
| ERPAC Friuli Venezia Giulia | Official regional inventory | Regional cultural heritage documentation |
| Trentino Cultura | Official provincial cultural source | Castle distribution, typological variety and contemporary cultural uses |
| Agenzia delle Entrate | Primary tax authority | General property purchase tax framework and tax base rules |
| Corpo Nazionale dei Vigili del Fuoco | Primary fire authority | Fire prevention regime for hospitality and accommodation activities |
| Ministero del Turismo | Primary tourism authority | National hospitality database and CIN framework |
| Impresa in un Giorno | Official business administration portal | Current standardized SCIA procedures for hospitality businesses |
| Regione Toscana, 2026 Works Price List | Official construction price source | Current basis for detailed construction cost estimating |
| Regione Emilia Romagna, 2026 Works Price List | Official construction price source | Current specialist restoration, conservation and structural work pricing framework |
| Horwath HTL Italy | Professional hospitality market research | Italian hotel construction and renovation cost benchmarks based on 50 cleaned projects |
| JamesEdition, Lionard and Idealista | Live real estate market sources | Current asking price evidence and scale of publicly marketed castle inventory |
| Published architectural and project sources for Reschio, Padernello, Ugento, Tabiano, Buttrio and Casole | Case study sources | Adaptive reuse models, programme, restoration scope and disclosed investment figures |